

What is the CSRD?
Corporate Sustainability Reporting Directive (CSRD)
Since 5 January 2023, the Corporate Sustainability Reporting Directive (CSRD) has established sustainability reporting obligations for companies. It replaced the previous Non-Financial Reporting Directive (NFRD). The CSRD aims to make sustainability information across the EU more transparent, consistent and comparable for investors, customers, regulators and the general public alike.
As a directive, the CSRD establishes the legal framework: which companies are required to report, when the requirements apply and how reporting must be carried out. The specific reporting requirements are set out in the European Sustainability Reporting Standards (ESRS), which form a separate, directly binding regulation alongside the CSRD. The two frameworks work hand in hand: without the CSRD, there would be no reporting obligation; without the ESRS, there would be no uniform set of reporting requirements.
The results are published in a dedicated section of the management report known as the sustainability statement. This statement is subject to an independent audit by a statutory auditor.
The originally broad scope of companies subject to reporting obligations has been significantly narrowed by the Omnibus Simplification Package – the EU legislative package aimed at reducing reporting requirements (Directive (EU) 2026/470). In future, companies falling below the following thresholds will no longer be directly required to prepare a sustainability statement.
Currently applicable thresholds (Directive (EU) 2026/470, in force since 18 March 2026):
EU companies will be subject to reporting obligations from the 2027 financial year if they meet both of the following criteria:
- More than 1,000 employees, and
- Net turnover exceeding €450 million.
Non-EU companies (with their registered office outside the EU) will be subject to reporting obligations if they:
- Generate turnover exceeding €450 million within the EU, and
- Have an EU subsidiary or branch generating turnover exceeding €200 million.
Germany must transpose the directive into national law by 19 March 2027. Until then, a transitional period applies in Germany, allowing companies to prepare for the new thresholds, although a definitive national legal basis has yet to be established.
Under the CSRD, companies must integrate their sustainability information into a dedicated section of the management report, known as the sustainability statement. The management report forms part of the annual report and supplements the financial statements with additional information on the company’s financial position and business performance.
The content of the report must comply with the binding European Sustainability Reporting Standards (ESRS). In terms of format, the report must also be prepared in ESEF (European Single Electronic Format), a standardised electronic reporting format used across the EU. Within this format, the reported metrics are made machine-readable through XBRL tagging (XBRL = eXtensible Business Reporting Language). Each data point is assigned a digital “label” that enables regulators, investors and analytical software to automatically extract and compare the data. The technical requirements for XBRL tagging are currently being revised.
A final, revised taxonomy is expected by the end of 2026.
- Learn More: ESRS Standards in Detail
- Download: ESG Handbook 2026
- Blog: A Brief Overview of the CSRD
- Blog: CSRD for Small and Medium-Sized Enterprises
- Blog: Update: EU Omnibus Initiative
- Webinars & Training: Practical Insights into ESRS and CSRD – Live or On Demand
Sustainability still matters
Is your Company below the Thresholds?
You are no longer directly subject to reporting obligations, or may no longer be required to report. However, that does not mean sustainability is off the agenda. Customers, banks and investors continue to request sustainability data, and many companies want to use ESG (environmental, social and governance) as a management tool in its own right. There are generally two approaches to voluntary reporting:
Voluntary Standard (VS)
A streamlined standard for companies that are not subject to CSRD reporting requirements. It is ideal if you want to respond to supply chain requests in a structured way and get started with manageable effort.
Voluntary Reporting in Accordance with the ESRS
Report voluntarily in accordance with the ESRS: Use ESG as a management tool, meet your business partners’ data requirements, and systematically develop your sustainability data.
Let’s discuss which approach is right for you in an initial consultation →
Assurance
Where First-Time Reports often fall short – and how to avoid these Pitfalls
A CSRD report, or sustainability statement within the management report, is assessed based on whether the statements made can be substantiated and adequately documented during the assurance process.
Our experience with first-time reporting projects has consistently revealed the same five weaknesses:
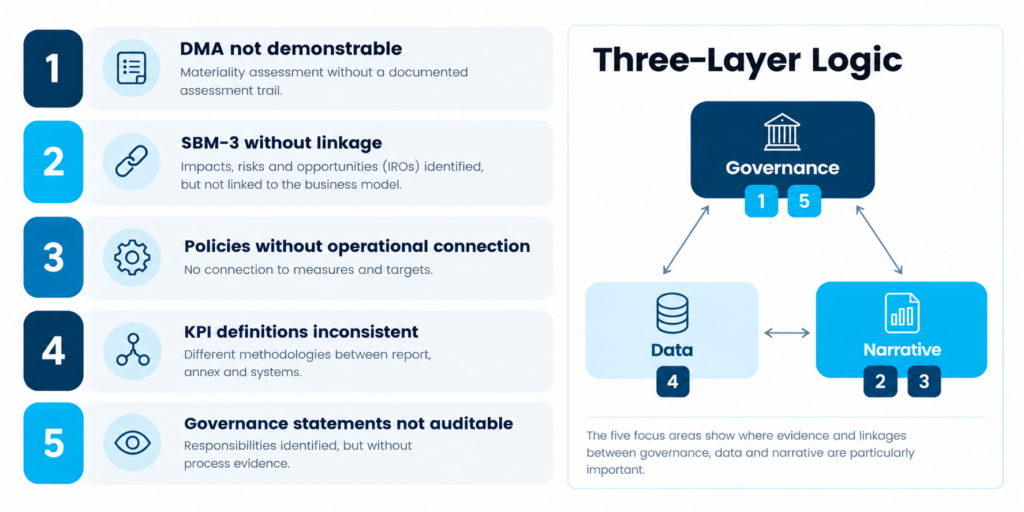
What matters is not the volume of data, but how it all connects. Sustainability reporting becomes auditable only when the links between the materiality assessment, policies, actions, targets and metrics are clearly documented and traceable. Without these connections, disclosures remain incomplete, actions lack clear links to targets, and statements are difficult for auditors to verify.
An auditable report therefore follows a consistent, traceable chain – from the materiality assessment through to the metrics.
Services
The DFGE Approach – Building an Audit-Ready CSRD Report
The starting point is the Double Materiality Assessment (DMA). It identifies the sustainability topics relevant to your company and assesses their impacts, risks and opportunities – both from the perspective of your company’s impact on the environment and society and from a financial perspective.
What you gain: A methodologically documented, audit-ready assessment of materiality results, with clear justification for every topic included or excluded – providing the foundation for all subsequent steps in preparing your sustainability statement.
The materiality assessment is followed by the implementation plan. We identify the relevant ESRS data points, compare them with your existing information, and highlight gaps and areas requiring action. Based on these findings, we develop a tailored roadmap towards a technically compliant CSRD report, with clear milestones and realistic planning.
What you gain: A thorough analysis of your current status, a transparent overview of data gaps, and a concrete roadmap including estimates of timelines, effort and costs.
In the third step, we prepare the complete, audit-ready technical CSRD report. We define documentation and evidence requirements, provide suitable templates and tools, and review disclosures for traceability and consistency. Where needed, we offer software-supported, technology-neutral assistance – without tying you to any specific tool.
What you gain: A consistent, audit-ready CSRD report, including all supporting evidence and documentation required for the external audit.
Optional Add-On Modules – Tailored to Your Needs
Beyond the three core modules, you can expand your CSRD project with specific add-on modules – available individually to suit your company’s ambitions and level of maturity.
All add-on modules can be flexibly combined with our core modules – get in touch to discuss your needs.
Your Advantages
Why Choose DFGE for Your CSRD Reporting?
- Personal, approachable consulting: Dedicated points of contact instead of constantly changing project teams – we support you throughout the entire process, not just at selected stages.
- Audit-ready methodology as standard, not an extra: We work from an auditor’s perspective and maintain detailed process documentation. Both are included in the scope of every project.
- Technology-agnostic approach: Software-supported where needed, without being tied to specific tools. You decide which solutions best fit your existing systems.
- A strong ESG foundation: Our research heritage and extensive experience with carbon accounting, ESG ratings and platforms such as EcoVadis and CDP combine methodological rigour with in-depth reporting expertise.
-
Over 25 years of experience: We support companies, particularly SMEs, with sustainability projects and reporting in accordance with international standards such as TCFD, GRI and UNGC – long before the CSRD was introduced.
FAQ | Frequently Asked Questions About the CSRD
1. When does my Company need to start Reporting under the CSRD?
In brief: EU companies will be required to report from the 2027 financial year if they have more than 1,000 employees and net turnover exceeding €450 million; both criteria must be met. Separate thresholds apply to non-EU companies. For a detailed overview of all criteria, see the section “Who Is Affected?”
Germany is expected to transpose the directive into national law by 19 March 2027. Until then, a transitional period applies, with no definitive national legal framework in place. Companies approaching the thresholds should monitor their growth and clarify in good time whether they may fall within the scope of the reporting requirements.
2. How much does a CSRD Report cost?
Providing a flat-rate figure would be misleading, as costs depend primarily on your starting point. The main cost drivers are the number of material topics, the availability of your data, the complexity of your corporate structure (e.g. the number of legal entities and locations), and any existing ESG groundwork, such as a carbon footprint assessment or previous sustainability reports.
In general, there are four types of costs: one-off setup costs (processes, data collection and internal resources), ongoing annual reporting costs (staff and external consulting), external assurance fees charged by your auditor, and the costs of digital tagging (XBRL tagging).
The simplified ESRS aim to reduce the reporting burden compared with the initial version. A reliable estimate of the costs involved is provided in Module 2, the implementation plan, which includes a robust assessment of the required effort and costs before you commit time and budget.
During a free initial consultation, we can provide a preliminary assessment of your current situation.
3. Does the Sustainability Statement need to be independently assured?
In brief: Yes. The sustainability statement included in the management report must be subject to an independent audit by a statutory auditor, providing limited assurance. The auditor expresses a conclusion in negative form, stating that nothing has come to their attention to indicate that the statement contains material misstatements.
Under the CSRD, the audit covers not only the disclosures themselves, but also their compliance with the ESRS, the process used by the company to determine the reported information (in practice, particularly the materiality assessment), and the digital tagging of the disclosures.
This is why documenting these processes is so important. For more details, see the section “Where First-Time Reports Often Fall Short During Assurance”.
The sustainability report prepared for external communication is separate from the sustainability statement and is not subject to this audit.
4. What is XBRL Tagging, and why does it matter for my Sustainability Statement?
XBRL tagging makes the metrics in your sustainability statement machine-readable. It is based on the XBRL taxonomy – the technical framework that defines which digital tag corresponds to each ESRS data point. This enables regulators, investors and analytical software to automatically compare data across companies and countries.
For your company, this means that the tagging must be carried out in ESEF format, is part of the external audit, and requires dedicated software or a service provider. A final taxonomy adapted to the simplified ESRS is expected by the end of 2026 (as of October 2026).
Plan for tagging from the outset to prevent it from becoming a bottleneck at the end of your reporting project.
5. How long does it take to prepare the first Audit-Ready Sustainability Statement?
This depends largely on your starting point. Companies without existing sustainability structures should allow at least 12 months for the double materiality assessment, implementation planning and preparation of their first report. The actual timeline depends on data availability, corporate complexity and any existing ESG groundwork, such as previous voluntary sustainability reports or carbon footprint assessments.
Companies with robust preparatory work in place can often reach their goal more quickly, while highly diversified corporate groups with complex supply chains generally require more time.
In any case, starting early provides a valuable buffer for preparing for the subsequent assurance process and helps avoid time pressure in the final stages of report preparation and the audit.
