

What are the ESRS?
European Sustainability Reporting Standards (ESRS)
The European Sustainability Reporting Standards (ESRS) are the mandatory EU standards for sustainability reporting. They define what companies must report on environmental, social and governance (ESG) matters and how this information must be presented – covering topics ranging from greenhouse gas emissions and working conditions throughout the supply chain to anti-corruption measures.
The aim of the ESRS is to make sustainability information comparable and reliable across Europe – in much the same way that international accounting standards provide a common framework for financial reporting.
The ESRS are developed at a technical level by the European Financial Reporting Advisory Group (EFRAG). They become legally binding when the European Commission adopts them as a Delegated Regulation.
Important distinction: The ESRS govern how sustainability reporting is carried out – including its content, structure and level of detail. The question of which companies are subject to reporting requirements and when these requirements apply is governed by the Corporate Sustainability Reporting Directive (CSRD). The relevant thresholds and reporting deadlines can be found on our CSRD page.
- Want to know whether your company is subject to sustainability reporting requirements? Find the scope, thresholds and details of our services on the CSRD page.
- Blog post: ESRS E1 and the requirements for the Corporate Carbon Footprint
- Blog post: Implementing ESRS S1 – Own Workforce
- Webinars & training: Practical knowledge on ESRS and CSRD – live or on demand
The Structure of the ESRS
12 Standards in 4 Groups
The ESRS comprise 12 individual standards, divided into four groups. Not every standard is equally relevant to every company: only the two cross-cutting standards are mandatory for all companies subject to reporting requirements. The ten topical standards are subject to the double materiality assessment – the process of determining which sustainability topics are actually relevant to the company’s business and its stakeholders. Only topics identified as material need to be reported on in detail.
Environment (E1-E5)
- ESRS E1 | Climate Change – greenhouse gas emissions, climate targets and transition plans
- ESRS E2 | Pollution – air, water and soil pollution, and pollutants
- ESRS E3 | Water and Marine Resources – water consumption, withdrawal and discharge
- ESRS E4 | Biodiversity and Ecosystems – impacts on biodiversity and habitats
- ESRS E5 | Resource Use and Circular Economy – material use, waste and recyclability
Social (S1-S4)
- ESRS S1 | Own Workforce – working conditions, diversity, health & safety
- ESRS S2 | Workers in the Value Chain – working conditions at suppliers and business partners
- ESRS S3 | Affected Communities – impacts on local communities
- ESRS S4 | Consumers and End-users – product safety, data protection and responsible marketing
Governance (G1)
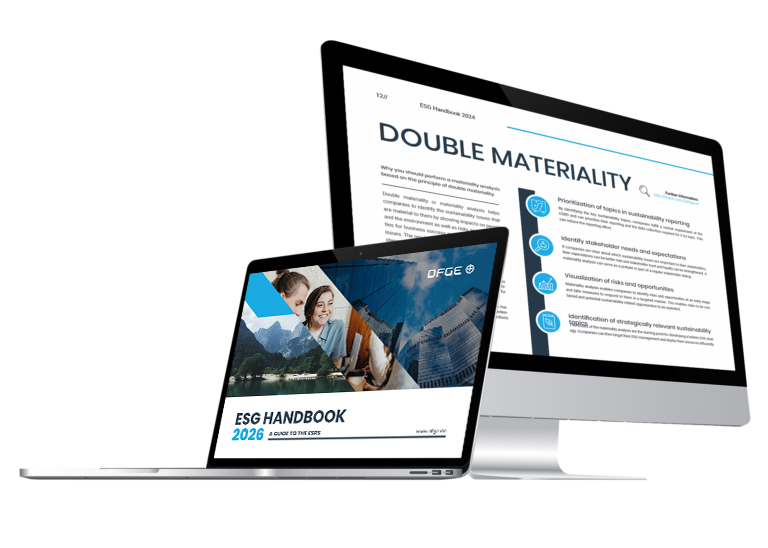
NEW: The DFGE ESG Handbook 2026
A Guide to the ESRS
Our brand-new ESG Handbook 2026 provides an introduction to the CSRD and ESRS standards, along with fact sheets featuring definitions and practical recommendations to help you navigate the rapidly evolving ESG landscape, answer key questions, and gain a clear overview of the ESRS standards.
A Brief Overview of the Regulatory Status
From the First ESRS Set to the Current Version
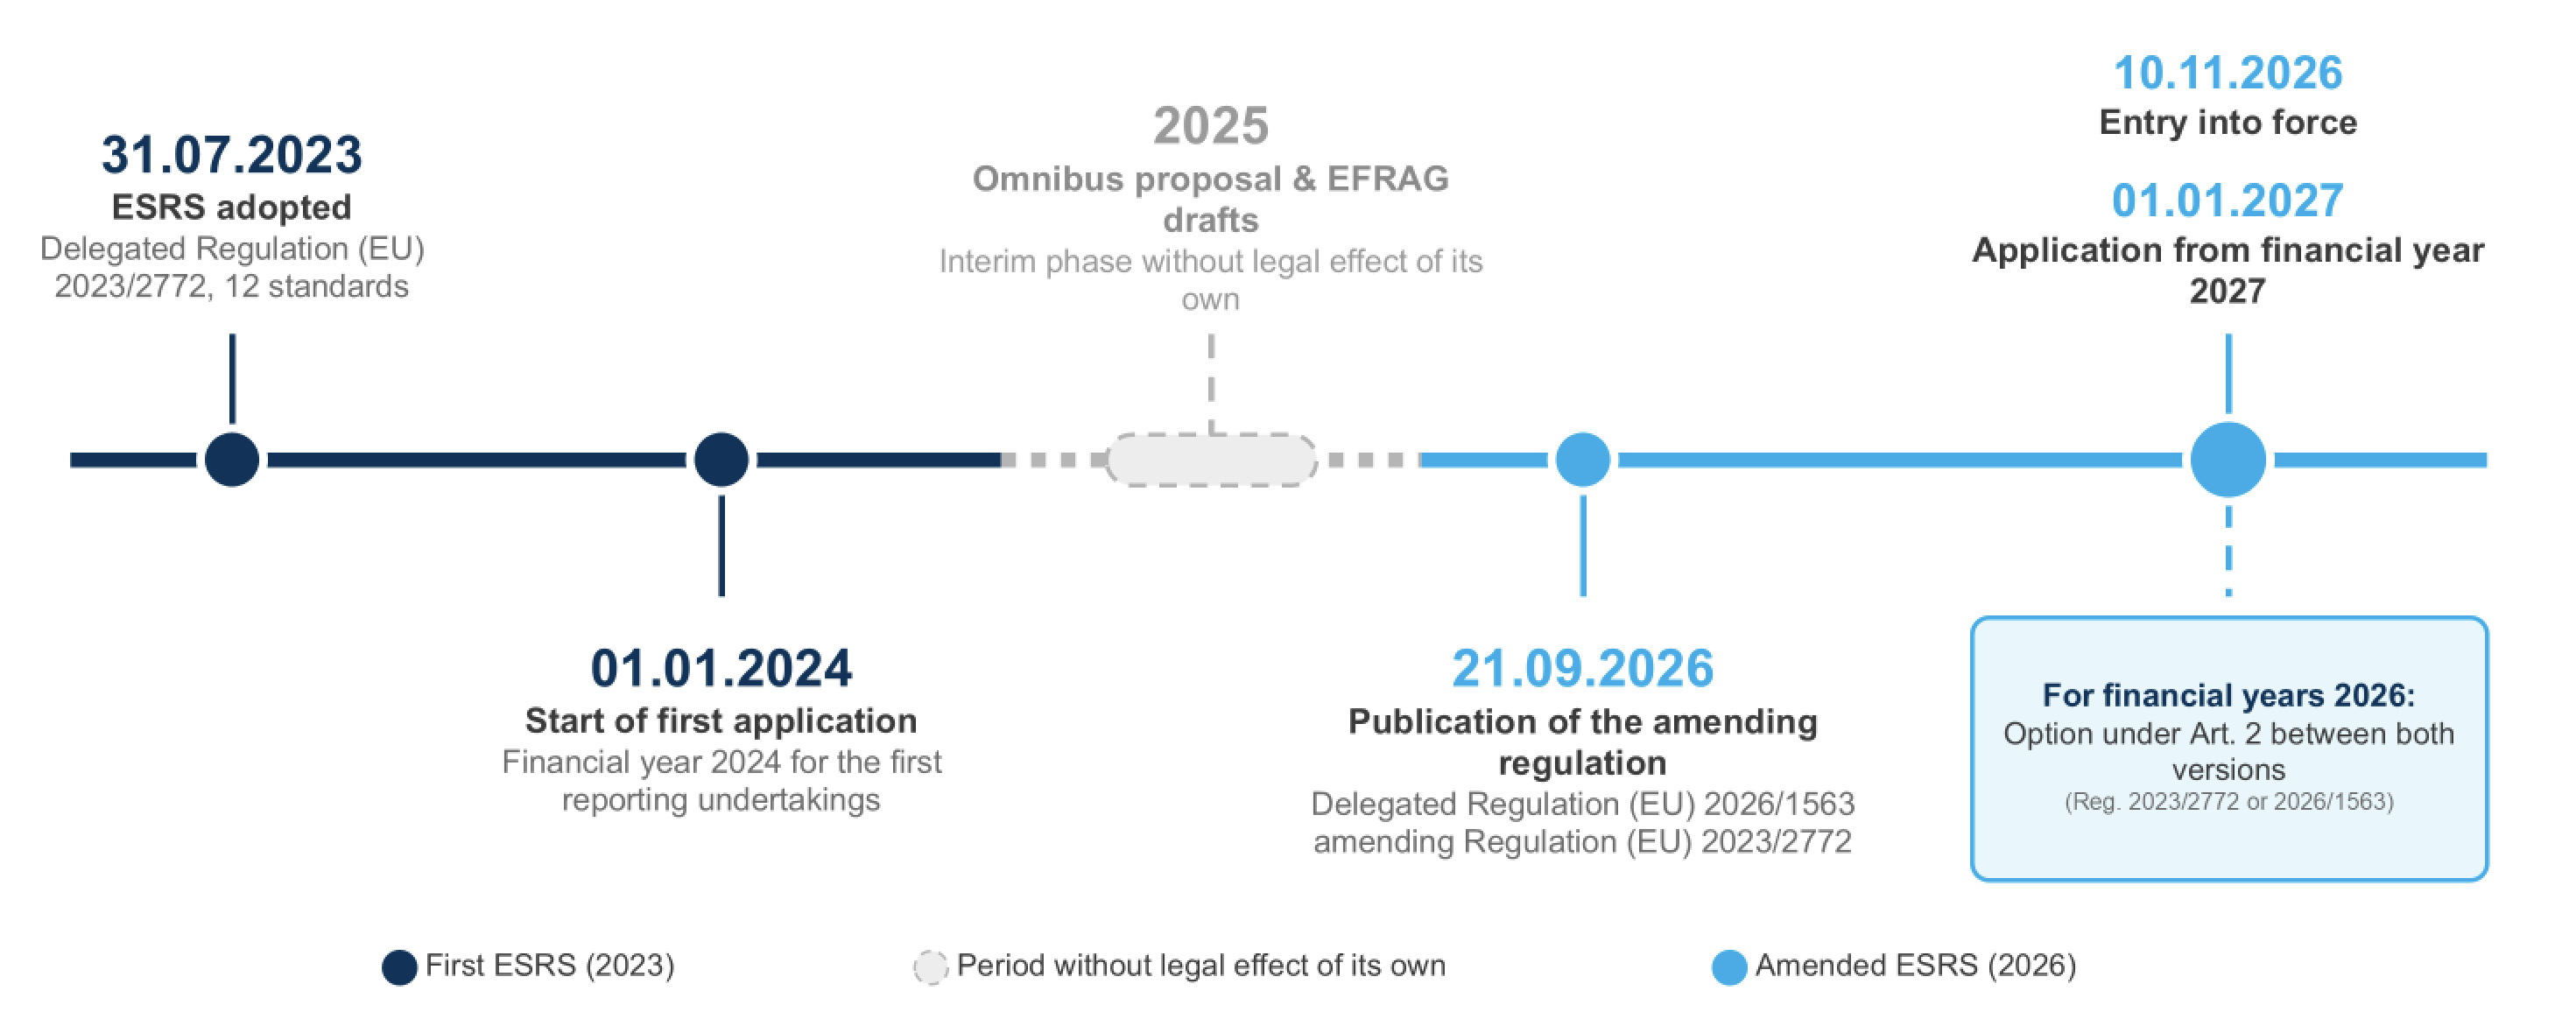
In 2023, the European Commission adopted the first set of ESRS (Delegated Regulation (EU) 2023/2772), comprising around 1,100 data points across all 12 standards. As a Delegated Regulation, it is directly applicable and legally binding in all EU Member States; no separate transposition into German law is required. From financial year 2024 onwards, companies that were already subject to reporting requirements had to report in accordance with the ESRS. A phased introduction was envisaged for additional companies.
However, initial practical experience showed that the large number of data points and the high proportion of narrative disclosures resulted in a significant reporting burden. As part of the EU Omnibus simplification package, a revision was therefore initiated in 2025. The main objectives were:
- fewer mandatory data points,
- a stronger focus on quantitative rather than narrative disclosures, and
- no additional sector-specific standards.
On this basis, the European Commission adopted the simplified version, Delegated Regulation (EU) 2026/1563, published on 21 September 2026. It applies to financial years beginning on or after 1 January 2027.
For financial year 2026, companies have a choice: They may either continue to report under the 2023 version of the ESRS or already apply the simplified 2026 version. The version selected should be clearly stated in the report, as it directly affects the scope and structure of the data to be collected.
FAQ: Frequently Asked Questions about the ESRS
1. What exactly has changed between the 2023 ESRS and the simplified 2026 ESRS?
The original ESRS (Delegated Regulation (EU) 2023/2772, “Set 1”) contained around 1,100 data points across 12 standards, a significant proportion of which had to be reported as free-form narrative text rather than as structured metrics.
The simplified version (Delegated Regulation (EU) 2026/1563, finally published on 21 September 2026, entering into force on 10 November 2026 and applicable to financial years beginning on or after 1 January 2027) significantly reduces the number of mandatory data points, prioritises quantitative over narrative disclosures, and provides a clearer distinction between mandatory and voluntary data points.
In addition, ambiguous wording has been clarified and the application of the materiality principle has been further specified, giving companies and auditors a more consistent understanding of what actually needs to be reported.
The basic structure of the 12 standards and the four standard groups remains unchanged – the revision represents a streamlining of the content rather than a structural reorganisation.
2. Which version of the ESRS do I need to apply for the 2026 financial year?
For financial years 2026, Article 2 of Regulation (EU) 2026/1563 provides companies with a choice: they may either continue to report under the original version (Regulation (EU) 2023/2772) or already apply the simplified version. From financial years beginning on or after 1 January 2027, the simplified version is mandatory for all companies.
This is not merely a formal choice: companies that are already well advanced in preparing their 2026 sustainability report and have collected data points based on the original version can avoid additional transition work by continuing to use that version. Companies that are still at an early stage, on the other hand, can build their reporting process directly around the leaner, simplified version and avoid duplicating their efforts.
Which option makes more economic sense in an individual case depends on the current project status, the existing system architecture and the group reporting structure. The decision should therefore be made at an early stage, as the version selected must be explicitly stated in the report.
3. Do I have to report on all 12 ESRS standards in full?
No. Only ESRS 1 (General Requirements) and ESRS 2 (General Disclosures) are mandatory for all companies subject to reporting requirements, without exception, as they establish the fundamental reporting principles and mandatory baseline disclosures on governance, strategy and risk management.
The ten topical standards (E1–E5, S1–S4 and G1), by contrast, are subject to the double materiality assessment: only topics that are considered material both in terms of the company’s impacts on people and the environment and in terms of financial opportunities and risks need to be reported on in detail.
A topic assessed as not material may be excluded entirely, provided there is a comprehensible and documented justification. However, this justification itself is regularly scrutinised critically by auditors and must be methodologically robust.
In practice, most mid-sized companies therefore report fully on only 4 to 7 of the 10 topical standards.
4. Are the ESRS compatible with other standards such as GRI?
There is partial, but not full, interoperability: According to market analyses, existing GRI reporting is estimated to fully cover around 40% of ESRS data points and partially cover a further 15%; the remaining data points need to be collected separately.
EFRAG and the Global Reporting Initiative (GRI) have formalised their cooperation and published an official interoperability index that shows, data point by data point, where overlaps exist.
In practice, this means that an existing GRI report provides valuable groundwork, as reporting structures and data sources can partly be reused, but it does not replace ESRS-compliant reporting. Conversely, companies reporting under the ESRS automatically fulfil a substantial part of the GRI requirements and can, if desired, additionally state that they report “with reference to GRI.”
Note: These percentages are based on commonly used market analyses rather than legally binding provisions and should therefore be regarded as indicative figures.
5. Will there be sector-specific ESRS standards in the future?
No. Originally, the ESRS framework envisaged a second set of sector-specific standards covering industry-specific sustainability topics – for example, for the automotive, textile or energy sectors – in addition to the 12 sector-agnostic standards. As part of the Omnibus simplification package, however, the European Commission has abandoned these plans entirely in order to avoid further increasing the overall number of mandatory data points and to limit the reporting burden for companies.
Going forward, there will be a single, sector-agnostic set of 12 standards for all companies subject to reporting requirements, regardless of their industry or business model.
Instead, companies should take industry-specific characteristics into account as part of the double materiality assessment within the existing topical standards, rather than waiting for additional, separate standards.
You now know what ESRS means.
But what does it mean for you specifically?
